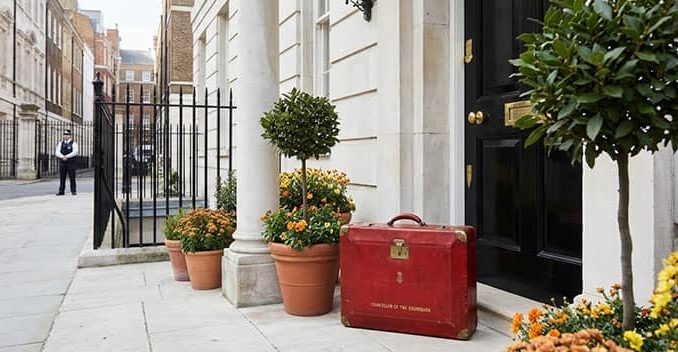
Economic policy is rarely a masterclass in frictionless perfection; more often, it is an exercise in brutal trade-offs. When Chancellor John Healey rose to dispatch the Autumn Budget, he did so against a global macroeconomic backdrop defined by jittery bond markets, stubborn inflationary ghosts and the creeping anxiety of households caught in a relentless cost-of-living squeeze. The narrative spun by Whitehall is one of dual purpose: immediate relief for the weary high street and domestic kitchen table, coupled with bold, structural reindustrialisation designed to future-proof the British economy for the next decade.
Yet, to look at this fiscal package through a purely partisan lens is to miss the sharper, harder-nosed reality that businesses and entrepreneurs grapple with every single morning. Critics will point out that many of the changes feel incremental—tweak here, a temporary surcharge there—while optimists see the foundational architecture of a modern, green, AI-accelerated industrial strategy. The truth, as is customary in complex economies, resides in the uncomfortable friction between immediate tax mechanics and long-term capital formation.
For the commercial sector, the Autumn Budget presents a fascinating paradox. On one hand, targeted interventions like the British Industrial Competitiveness Scheme and permanent perks for founders offer genuine oxygen for scaling businesses. On the other, the heavy lifting of paying for these measures falls squarely on targeted tax adjustments—most notably the temporary doubling of the Bank Corporation Tax Surcharge and increased levies on property and savings income. It is a calculated gamble by the Treasury: squeeze select capital pools today to fund energy security, defence spending and infrastructure tomorrow.
As we dissect the mechanics of this Budget, we must look past the political theatre and examine what it actually means for the balance sheet of the nation. Does this fiscal statement provide sustainable momentum for British enterprise, or is it merely a well-packaged holding pattern? Let us examine the core pillars of the Chancellor’s blueprint, breaking down the numbers, the business implications and the hard-headed realities facing commerce today.
Breathing Space and Household Relief: The Politics of the Kitchen Table
The immediate headline of the 2026 Autumn Budget was unapologetically populist: immediate respite for families grappling with structural cost pressures. With household energy bills remaining a primary driver of consumer anxiety, the government rolled out a £100 Household Energy Payment for up to 20 million homes across England in bands A to D for 2027, backed by equivalent Barnett allocations for the devolved nations. Furthermore, the temporary VAT cut on electricity bills has been extended until 1 July 2027, shaving roughly £50 off the Ofgem annual price cap.
Crucially, how this is funded tells us everything about the Treasury’s current calculus. The relief is underwritten by increasing the Bank Corporation Tax Surcharge from 3% to 6% for a strict 15-month window, raising an estimated £1.5 billion before sunsetting in March 2028. For high street consumers, the abolition of gas standing charges in favour of unit rates represents a welcome structural shift toward fairness, giving households direct agency over their energy outlays.
From a retail and commerce perspective, however, putting cash back into consumer pockets via energy relief and a 3.9% rise in the National Living Wage (pushing it to £13.21 per hour from April 2027) is a double-edged sword. While it stimulates domestic consumption and high-street footfall, it simultaneously ramps up operational overheads for low-margin employers in hospitality and retail. Business owners must now absorb a £910 gross annual earnings increase per full-time worker on the minimum wage, testing resilience right down to the independent shop floor.
Motorists and Logistics: Keeping the Wheels of Commerce Turning
Transport is the circulatory system of the British economy, and any disruption to fuel pricing immediately ripples through supply chains, wholesale logistics and retail pricing. Recognising this vulnerability, the Chancellor extended the 5p cut to fuel duty for a further six months and deferred the planned Retail Prices Index (RPI) increase until 1 July 2027.
When aggregated across the parliament, the Treasury calculates that these adjustments save the average car driver £230, large goods vehicle operators £472, and heavy goods drivers nearly £4,000 compared to prior trajectories, rendering petrol and diesel 15p per litre cheaper than previously scheduled from April 2027. More importantly for the gig economy and field-based enterprises, the permanent increase in tax-free mileage rates injects vital liquidity into the pockets of the estimated two million employees and one million self-employed individuals who rely on their vehicles for trade.
Simultaneously, the administration is attempting to de-risk the transition to electric vehicles (EVs). Recognising that soaring public charging tariffs threaten to stall EV adoption among urban drivers without off-street parking, the Budget implements targeted price cuts at local, lower-powered public chargers—saving regular users an estimated £150 annually. For fleet managers and commercial operators, these measures offer a predictable, cost-managed horizon during a turbulent energy transition.
High Streets and Corporate Rates: A Lifeline for Retail and Hospitality
For years, the commercial property tax regime has been cited by business lobby groups as an existential anchor dragging down Britain’s high streets. The 2026 Budget attempts a radical surgical intervention. Under the new package, all retail, hospitality and leisure properties in England will see their business rates either frozen in real terms, reduced or cut entirely to zero.
By lifting the Small Business Rates Relief threshold, approximately 70,000 additional high-street businesses will be taken out of business rates altogether, meaning half of all retail, hospitality and leisure properties will pay zero business rates. This is paired with a two-year real-terms freeze across the sector. To fund this £-billion-scale giveaway without bloating national debt, the Treasury turned to digital enforcement and sin taxes: closing non-compliance loopholes on online marketplaces, increasing gambling taxes on high-risk machine games, and stripping business rates reliefs from vape shops and adult gaming centres to refocus public support on community-anchor pubs, cafés and independent shops.
For industrial manufacturers, the intervention is equally stark. The introduction of the British Industrial Competitiveness Scheme from April 2027 will cut electricity bills by up to 25% for over 10,000 eligible businesses in electricity-intensive foundational sectors, bridging the uncompetitive energy-cost gap that has long disadvantaged British heavy industry relative to continental European competitors.
Housing and Infrastructure: Unlocking the Land Supply
Housing is not merely a social crisis; it is an economic bottleneck that constrains labour mobility and starves regional productivity. The 2026 Budget commits an additional £1.5 billion for social and affordable housing—taking total capital investment over the decade past £40 billion—while the newly minted Your First Home Scheme aims to usher 70,000 aspiring buyers onto the property ladder.
From a developer’s perspective, the most pragmatic stroke in the housing package is the exemption of smaller housing developments on brownfield land from onerous Biodiversity Net Gain requirements. By cutting bureaucratic red tape and lowering initial planning friction, the government is incentivising private developers to unlock brownfield sites that have languished under regulatory weight. Furthermore, streamlining the planning process and addressing legal delays through upcoming infrastructure legislation signals a welcome departure from decades of paralysis that turned major civil engineering projects into multi-year legal soap operas.
Industrial Strategy, AI, and Capital Investment: Backing the Future
Growth cannot be legislated into existence; it must be engineered through targeted capital deployment. The Treasury’s decision to inject an additional £20.4 billion into the National Wealth Fund and the British Business Bank—including £15.4 billion for the National Wealth Fund and £2 billion dedicated to a new Energy Wealth Fund—represents a significant mobilisation of state-backed capital designed to crowd in private institutional investment.
In the advanced manufacturing and life sciences sectors, this reindustrialisation strategy is already bearing fruit. A multi-decade partnership with Rolls-Royce, anchored by a joint 10-year, £2.5 billion programme, will develop next-generation gas turbine technology for civil and defence aerospace, securing thousands of high-value engineering jobs. Similarly, over £1 billion in public-private life sciences investments—featuring major R&D hubs by Convatec in Manchester, Vertex in Oxford, and Kindeva in Loughborough—cements the UK’s position as a life sciences superpower.
On the technological frontier, the £700 million AI package is both protective and productive. Rather than adopting an uncritical Silicon Valley accelerationist stance, the government is ring-fencing £120 million for the AI Security Institute, establishing a world-first national capability to investigate agentic security incidents, and funding the Sovereign AI Unit to ensure domestic tech scale-ups retain a sovereign footprint. For entrepreneurs, the introduction of a new Founders Relief—offering a reduced 10% Capital Gains Tax rate on up to £10 million of lifetime gains for innovators who scale and reinvest in UK companies—provides a world-class tax incentive to keep home-grown talent anchored in Britain.
The Verdict: Pragmatism Over Perfection
The Autumn Budget 2026 is an unmistakable reflection of political and economic realism. It does not pretend that the UK economy is careening toward frictionless utopia; rather, it acknowledges that stagnant productivity, volatile energy markets and crumbling public infrastructure require targeted, state-backed intervention paired with commercial incentives.
For the business community, the package offers a complex mixture of relief and responsibility. High street retailers and industrial manufacturers receive tangible oxygen through rates freezes and energy tariff interventions. Entrepreneurs gain powerful tax architecture through Founders Relief and enhanced venture capital pathways. Yet, these benefits are balanced by targeted tax extraction on banking profits, savings, and property income.
Ultimately, the test of this Budget will not be found in the headlines of today, but in the hard metrics of tomorrow: whether private capital flows into our regions, whether infrastructure projects break ground without endless legal delay, and whether British businesses find the confidence to invest, scale, and conquer global markets.
Have Your Say!
Does the Chancellor’s Autumn Budget strike the right balance between immediate cost-of-living relief and long-term industrial investment, or does increased tax extraction on savings and banking risk stifling entrepreneurial drive?
Join the conversation or follow us on facebook, instagram, youtube, TikTok, LinkedIn and X/Twitter or why not submit your own article! Or email at contribute@criticalmatters.net
Facts
- The UK Chancellor delivered the Autumn Budget on a platform of fiscal discipline, meeting the stability rule with £15 billion of headroom in 2029–30.
- The National Living Wage is scheduled to increase by 3.9% on 1 April 2027, rising to £13.21 per hour.
- The Bank Corporation Tax Surcharge will increase temporarily from 3% to 6% for 15 months, raising £1.5 billion before ending on 31 March 2028.
- Defence spending is backed by a fully funded £15 billion Defence Investment Plan, taking spending to 2.7% of GDP in 2027–28.
Links
- Review official fiscal projections and economic reports via the Office for Budget Responsibility.
- Access full legislative text and policy documents from GOV.UK HM Treasury.
- Explore economic analysis and commentary from the Institute for Fiscal Studies.

Be the first to comment